When Indian “Rupee” Ruled the Global Trade !!!
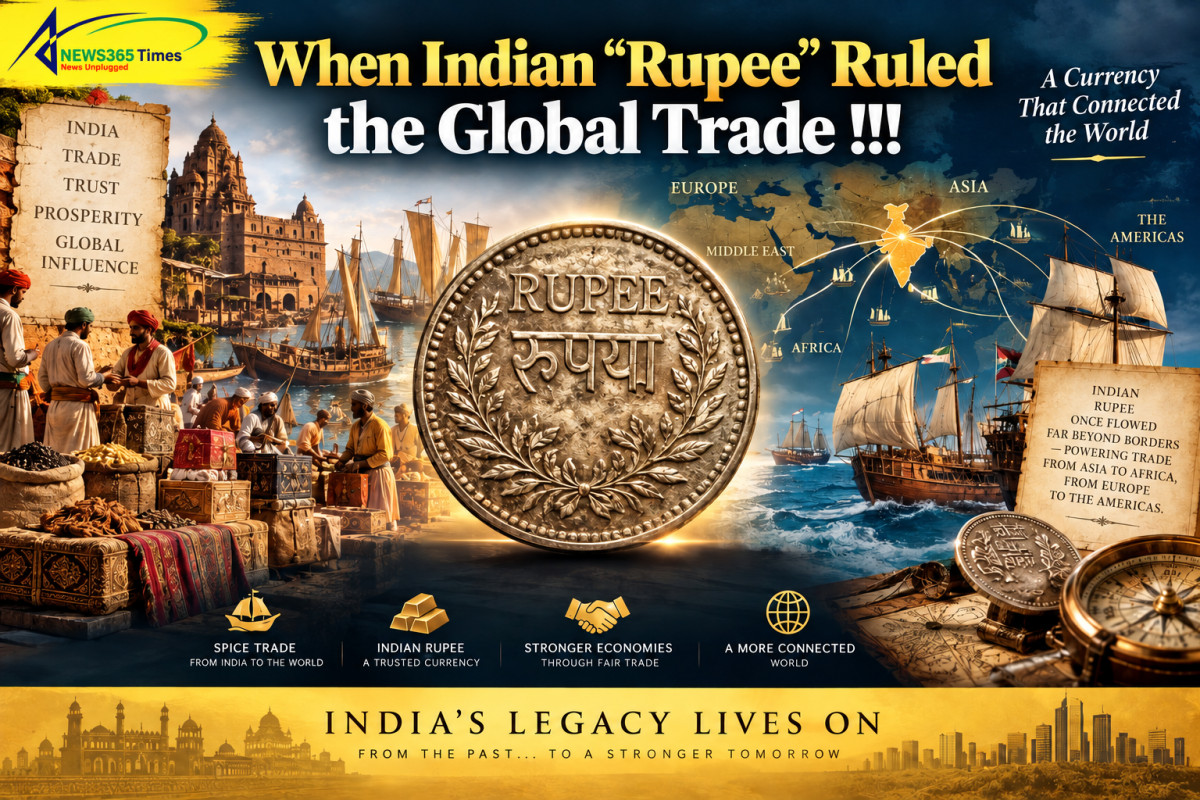
The name Rupiah (and its sister form, Rupee) traces back to the Sanskrit word rupaya, meaning wrought silver or stamped coin.
In 1540 to 1545, Sher Shah Suri reformed the monetary system of northern India by introducing a standardized 178-grain pure silver coin called the Rupiya. The Mughals retained it, and the British East India Company later adopted it as standard legal tender.
Because of the vast reach of Indian mercantile trade, British imperial administration, and maritime routes across the Indian Ocean, the Rupee became the de facto currency of many nations and territories:
The Persian Gulf & Arabian Peninsula: Dubai, Abu Dhabi, Qatar, Bahrain, Kuwait, and Oman used the Indian Rupee (and later the official Gulf Rupee issued by the Reserve Bank of India) as their primary official legal tender well into the 1950s and 1960s.
South Asia & the Himalayas: Ceylon (Sri Lanka), Nepal, Bhutan, and Burma (Myanmar) directly circulated or pegged their legal systems to the Indian Rupee.
East Africa & the Indian Ocean: Kenya, Uganda, Tanzania (Zanzibar), Mauritius, and Seychelles operated on Indian silver rupees through maritime trade across the Arabian Sea.
The Traditional System: From Daam and Anna to Decimalisation
Prior to 1957, the currency was not divided into 100 paise. It followed an ancient base of 16 fractional math system:
1 Rupee = 16 Annas = 64 Paise = 192 Pies
- Char Anna (4 Annas): 1/4 of a rupee (25 paise) nicknamed the chavanni.
- Aath Anna (8 Annas): 1/2 of a rupee (50 paise) the iconic athanni.
- Barah Anna (12 Annas): 3/4 of a rupee (75 paise).
On April 1, 1957, India passed the Indian Coinage (Amendment) Act and shifted to the metric decimal system: 1 Rupee was officially redefined as 100 Naye Paise (new paise). Over time, the word naya dropped off, and the anna faded into cultural idioms (such as "solah aane sach 100% true).
The Shift: How the Rupee Moved from 4.76 to 96+ per USD
At independence in 1947, the Indian Rupee was not floating; it was pegged directly to the British Pound Sterling at 1 Rupee = 1 Shilling 6 Pence (which made 1 USD roughly equal to 3.3 to 4.76 Rupees at the time).
Its journey to current levels was driven by distinct structural shifts: now let’s look at the milestones and at that moment where was Rupee vs USD
1947-1965 Post-Independence Industrialization with Large import bills for heavy machinery, grain imports (PL-480), and twin wars (1962 with China, 1965 with Pakistan) triggered massive budget and trade deficits. Rupee was at 4.76 to a USD.
The 1966 Devaluation: Severe droughts and drying foreign aid forced Prime Minister Indira Gandhi to devalue the rupee by 57.5% overnight to revive exports. Rupee moved to 7.5 to a USD.
Then from 1970’s to 1980’s, Oil Shocks & Managed Float. The collapse of Bretton Woods (1971 agreement to peg currency to USD after World War II ) and global oil crises pushed import bills up. India linked the rupee to a basket of currencies, and high domestic inflation steadily eroded its nominal value. Rupee moved to 17.5 to a USD.
During 1991 Balance of Payments Crisis: India's forex reserves shrank to barely three weeks of imports. The RBI airlifted gold reserves to London, followed by a two-step devaluation (19%) and the historic LPG (Liberalization, Privatization, Globalization) reforms. Rupee this time moved to 26 to a USD.
Starting 1993 till 2010 with Market-Determined Floating Rate, Rupee shifted to a market float. Persistent trade deficits, the 2008 Global Financial Crisis, and the 2013 "Taper Tantrum" saw ongoing depreciation as India's demand for crude oil and electronics outpaced exports. Rupee moved to 31 to a USD.
From 2010 till now we see that the Global Supply Shocks & Strong Dollar Cycles: Aggressive Federal Reserve interest-rate tightening cycles, geopolitical disruptions in crude oil markets, and persistent structural inflation differentials between the US and India gradually pushed the exchange rate past 90, touching the mid-90s to 96/97 per dollar.
A currency depreciating against the US dollar over several decades is not simply an indicator of weakness; it reflects macroeconomic fundamentals:
Purchasing Power Parity & Inflation Differential: For decades, India's domestic inflation typically averaged 5% to 8%, while US inflation hovered around 2%. When a nation experiences higher inflation than its trading partners, its currency must nominally depreciate to keep export prices competitive.
The Crude Oil & Energy Burden: India imports over 80% of its domestic crude oil requirement, priced in US dollars. Whenever global energy prices rise, India must sell rupees to buy dollars, creating structural downward pressure on the currency.
Move from Fixed Pegs to Free Markets: In the era of char anna and aath anna, the exchange rate was artificially fixed by government decree under tight capital controls. Today, the rupee is a market-determined currency reflecting daily capital flows, foreign institutional investment, and global trade dynamics.
The three distinct stages worth mentioning:
A. The Gold Smuggling Drain and the 1959 "Gulf Rupee"
In the 1940s and 1950s, the Indian Rupee was official legal tender in Kuwait, Bahrain, Qatar, Oman, and the Trucial States (modern UAE). The Reserve Bank of India (RBI) effectively served as the central bank for the Persian Gulf.
Because post-independence India placed strict curbs and high tariffs on gold imports, a thriving arbitrage trade arose:
Smugglers moved ordinary Indian banknotes into open Gulf markets (like Dubai and Kuwait) to buy gold.
The gold was ferried by dhows back to India, where domestic demand fetched enormous premiums.
Banks in the Gulf gathered surplus Indian rupees from these gold transactions and officially returned them to the RBI in Bombay, which was contractually obligated to convert them into British Pound Sterling.
India was effectively subsidizing illegal gold imports out of its official foreign exchange reserves. To plug this leak without disrupting Gulf commerce, the Indian Parliament enacted the Reserve Bank of India (Amendment) Act in May 1959, creating the Gulf Rupee (identifiable by distinct red/orange ink and special serial prefixes). It was non-repatriable and invalid within India itself, serving exclusively across the Gulf.
B. The Fatal Rupture: The June 6, 1966 Devaluation
The turning point came not from the Middle East, but from New Delhi.
By the mid-1960s, India was burdened by consecutive wars with China (1962) and Pakistan (1965), catastrophic monsoon droughts, and a severe balance-of-payments deficit. Under heavy pressure from the World Bank and the IMF, Prime Minister Indira Gandhi executed a sudden devaluation on June 6, 1966, slashing the Rupee's official value by 36.5% (raising the foreign exchange cost of a dollar by 57.5%, from 4.76 to 7.50 per USD).
Gulf monarchies received zero advance warning. Overnight, businesses, banks, and citizens across the Arabian Peninsula lost over a third of their wealth in international terms.
The Gulf states did not wait to renegotiate:
Qatar and Dubai immediately withdrew from the Gulf Rupee, briefly adopted the Saudi Riyal as emergency legal tender, and formed a joint currency board to release the Qatar & Dubai Riyal.
Abu Dhabi adopted the Bahraini Dinar (which Bahrain had created earlier in 1965).
Kuwait had already established the Kuwaiti Dinar at independence in 1961.
Only Oman held on until 1970, when Sultan Qaboos introduced the Saidi Rial.
India did not lose its regional currency status to a commercial pivot by the Gulf; it lost it because a domestic economic emergency in New Delhi undermined international faith in the currency.
C. Where Oil & the US Dollar Really Enter the Picture
The Petrodollar Accord (1973 - 1974): After President Nixon ended dollar-to-gold convertibility in 1971, the US and Saudi Arabia negotiated a pivotal agreement: Saudi Arabia (and subsequently OPEC) agreed to price and settle all crude oil exports solely in US Dollars in exchange for American military protection and arms.
The Rise of Sovereign Gulf Currencies: Flush with petrodollars from the 1973 OPEC oil embargo, the young Gulf currencies did not peg to the Rupee; they pegged to the US Dollar or SDR currency baskets.
The Inversion of Trade: India shifted from being the net financial anchor of the Indian Ocean to a major net consumer of Gulf energy. Instead of exporting currency to the Gulf, India now had to continuously export goods, labor, and domestic savings just to secure the US Dollars needed to import crude oil.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
English Daily News Platform #News #Latestupdates #Tech #Business #Politics #Indianews #India. Regd No : JMAGC/HR/00072 (JMAGC ), MIB ,Govt of India
Comments (0)